
Malta and Cyprus are the two EU islands that entrepreneurs compare most often when they look for a lower tax burden without leaving the European Union. Both use English in business, both have company law built on the British model and both sit inside the EU single market. Since 1 January 2026, though, the comparison has changed: Cyprus has raised its corporate tax to 15% and rewritten its dividend rules, while Malta keeps its refund system and is tightening its residence programmes from 2027.
This guide compares the two countries on company tax, dividends, personal tax, non-dom rules, set-up and residence, with the rules in force in 2026.
The short answer
- For a trading company whose shareholders live outside both islands, Malta usually costs less: about 5% effective tax on trading profits through the shareholder refund, against a flat 15% in Cyprus.
- For an entrepreneur who moves to Cyprus as a non-dom, Cyprus is hard to beat on dividends: no Special Defence Contribution for 17 years, only the 2.65% health contribution.
- Both islands let you pay tax on trading profits in a single payment: Cyprus at 15%, Malta at about 5% if the company sits in a fiscal unit with a Maltese holding company. Without that structure, a Maltese company pays 35% and the shareholder claims the refund afterwards.
- In both countries the company must really be managed where it is registered. A company run from another country can end up taxed there.
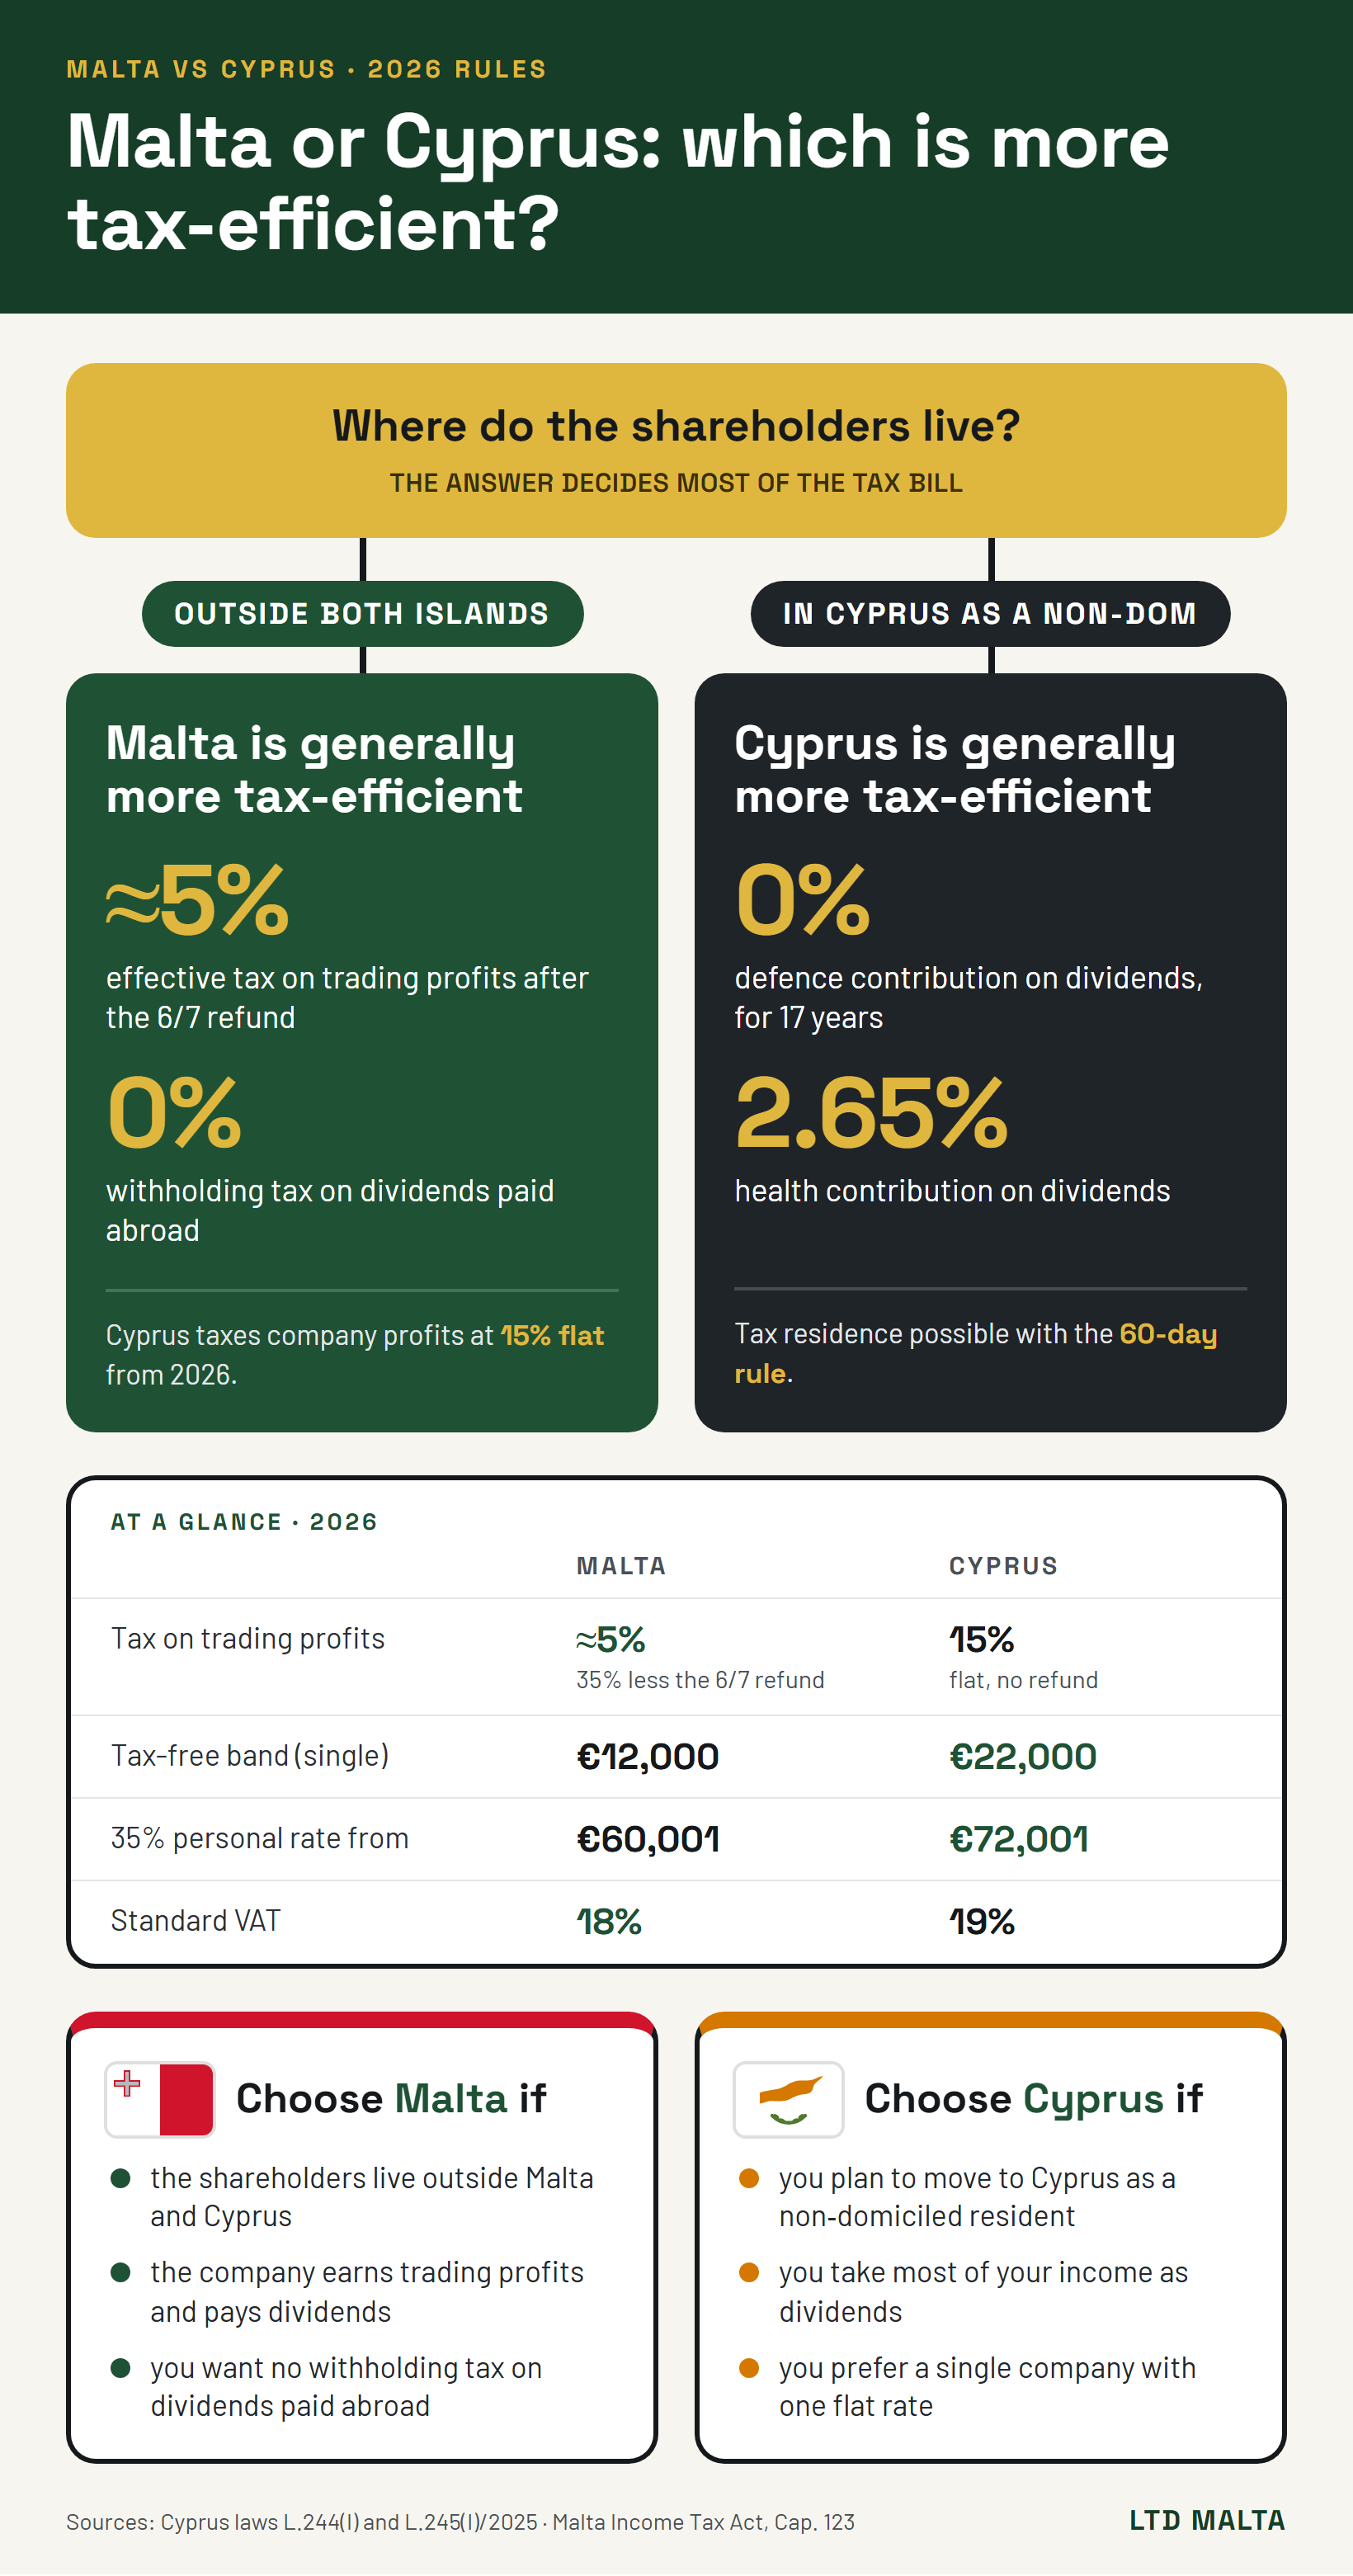
Malta vs Cyprus at a glance (2026)
| Malta | Cyprus | |
|---|---|---|
| Corporate tax rate | 35%, with shareholder refunds | 15% (12.5% until 2025) |
| Effective tax on trading profits | About 5% after the 6/7 refund | 15% |
| Optional flat regime | 15% final tax, no refunds (from 2024 profits) | None needed |
| Withholding tax on dividends to non-residents | None | None, except 5% or 17% to low-tax and blacklisted jurisdictions |
| Foreign dividends for resident non-doms | Taxed only if brought into Malta | 0% Special Defence Contribution for 17 of 20 years, 2.65% health contribution |
| Top personal tax rate | 35% above €60,000 | 35% above €72,000 |
| Tax-free band (single) | €12,000 | €22,000 |
| Standard VAT | 18% | 19% |
| Minimum share capital | €1,164.69, 20% paid up | No statutory minimum |
| Audit | Required for every company | Required for every company |
Corporate tax: Malta’s refund system against Cyprus’s new 15%
Cyprus taxes company profits at a flat 15% from 1 January 2026, up from 12.5%. The reform also extended loss carry-forward from five to seven years. The company pays its tax and the matter ends there, which keeps compliance simple.
Malta charges 35% on company profits, but shareholders can claim a refund when the company pays a dividend. For trading income the refund is six-sevenths of the tax paid, so the total burden falls to about 5%. Passive interest and royalties get a five-sevenths refund, about 10% overall. We explain the mechanism step by step in our guide to Malta’s 5% corporate tax.
Without a group structure, the refund has a cash-flow cost: the company pays the full 35% and the shareholder recovers the difference after filing a claim. Since 2019, the consolidated group rules let a Maltese holding company and a subsidiary it owns at 95% or more form a fiscal unit. The fiscal unit pays tax at the net rate straight away, about 5% on trading profits, and nobody files a refund claim (Consolidated Group (Income Tax) Rules, rule 6(2)). Since 2024 profits, Maltese companies can also opt for a 15% final tax with no refunds. That option does not lower the bill, so for most trading companies the refund or the fiscal unit remains cheaper.
Malta’s Budget 2027, presented on 26 October 2026, announced a 25% rate on profits that companies with a turnover of up to €1 million retain or reinvest. The start date and the conditions depend on rules not yet published. We follow the details in our article on the Budget 2027 measures for businesses.
On dividends received from subsidiaries, both countries offer a participation exemption, so holding companies are common in both. Cyprus has also kept its IP box, which exempts 80% of qualifying IP profit. At the new 15% rate the effective tax on that income rises to about 3%.
Dividends: the decisive difference
The two countries treat the shareholder very differently, and this point often decides the choice.
Malta levies no withholding tax on dividends paid to non-resident shareholders. A shareholder who lives outside Malta receives the dividend and the refund, and pays tax only where they live.
Cyprus taxes dividends of residents through the Special Defence Contribution (SDC). From 2026 the SDC on dividends for residents who are domiciled in Cyprus falls to 5% for profits earned from 2026 onwards, while dividends paid out of profits up to 2025 still bear 17%. A new 10% SDC applies to disguised dividends, such as personal use of company assets. Residents also pay the 2.65% GeSY health contribution on dividends, capped at €180,000 of income.
Cyprus has also abolished the deemed dividend distribution for profits from 2026. Under the old rule, 70% of profits not distributed within two years were treated as paid out. The rule still applies on a transitional basis to 2024 and 2025 profits.
Payments abroad are mostly free of withholding tax, with two exceptions introduced in 2026: 5% on dividends paid to companies in low-tax jurisdictions and 17% on those paid to companies in jurisdictions on the EU non-cooperative list.
Personal tax and non-dom rules
Both islands tax individuals at progressive rates up to 35%, and Cyprus has the more generous bands since 2026.
| Chargeable income band | Malta (single, 2026) | Cyprus (2026) |
|---|---|---|
| 0% | Up to €12,000 | Up to €22,000 |
| 15% / 20% | €12,001 to €16,000 at 15% | €22,001 to €32,000 at 20% |
| 25% | €16,001 to €60,000 | €32,001 to €42,000 |
| 30% | None | €42,001 to €72,000 |
| 35% | Over €60,000 | Over €72,000 |
Each rate applies only to the slice of income within its band.
For people who relocate, the non-dom regimes matter more than the bands.
- Cyprus: a non-domiciled resident pays no SDC on dividends and interest for 17 of the last 20 years of residence. After that period, a person can keep the exemption by paying a flat €250,000 for each five-year period, for up to two periods. Cyprus also exempts 50% of employment income above €55,000 for 17 years for people who were not resident in the previous 15 years.
- Malta: a resident who is not domiciled pays tax on Malta-source income and on foreign income brought into Malta. Foreign income kept abroad and foreign capital gains are not taxed. A €5,000 minimum tax applies when foreign income of €35,000 or more is not fully brought into Malta. Long-term and permanent residents are taxed on worldwide income, a rule we cover in our article on Malta’s 2027 individual tax rules.
To become tax resident, Cyprus offers the 60-day rule: at least 60 days in Cyprus, no more than 183 days in any other single country, a permanent home in Cyprus and a business, job or directorship there. Since 2026 you no longer need to prove that you are not resident elsewhere. Malta has no equivalent short-stay rule.
Cyprus taxes gains on crypto-assets at a flat 8% from 2026, and taxes capital gains only on Cypriot real estate and on shares that derive their value from it.
Substance: where the company is really managed
Both countries are EU members, and the tax authorities of your home country will look at where the company is actually run. If the directors take the decisions from Italy, Germany or France, that country can treat the company as its own tax resident and tax it at its own rates, whatever the Maltese or Cypriot rate.
Since 2026 a company incorporated in Cyprus is tax resident there by default, unless a tax treaty says otherwise. Malta has long treated companies incorporated in Malta as resident. In both cases the incorporation address settles the local rule, while real management decides the outcome under tax treaties and in your home country.
Setting up and running the company
- Registration: in Malta the Malta Business Registry registers companies online. You can read the full procedure in our guide to registering a limited company in Malta. In Cyprus the Registrar of Companies handles registration, and timing estimates vary widely between providers.
- Share capital: Malta requires at least €1,164.69, with 20% paid up. Cyprus sets no statutory minimum.
- Annual costs: both countries require audited accounts for every company. Cyprus abolished its €350 annual company levy from 2024.
- Language and law: English is an official language in Malta. In Cyprus the official languages are Greek and Turkish, while English is widely used in business.
Residence for non-EU nationals
Malta is replacing its residence tax programmes with the Individual Tax Programme from 1 January 2027: 15% on foreign income brought into Malta, a minimum tax of €35,000 a year and a property of at least €700,000 or a rent of €14,000 a year. Applications received by 31 December 2026 keep the current terms until 2031. Our residence and relocation service covers both routes.
Cyprus grants permanent residence to non-EU nationals who invest at least €300,000 plus VAT, for example in a new property, and who show foreign income of at least €50,000 a year. The criteria have not changed since 2023. A bill to restrict property purchases by non-EU buyers was still under discussion in September 2026.
Malta and Cyprus compared
Malta
Better for trading companies
- About 5% effective tax on trading profits
- No withholding tax on dividends to non-residents
- Non-doms taxed only on income brought into Malta
- Residence programme from 2027 with a €35,000 minimum tax
Cyprus
Better for resident non-doms
- 15% flat corporate tax from 2026, no refunds
- 0% SDC on dividends for non-doms for 17 years
- Wider personal tax bands, 0% up to €22,000
- 60-day rule for tax residence
When Malta, or Cyprus, is the wrong choice
- Malta is a poor fit if the structure has only a few thousand euro of profit: audit and compliance costs absorb the saving, and paying 5% straight away requires a second company for the fiscal unit.
- Cyprus loses its edge when the shareholders live outside Cyprus: the company pays 15% and the non-dom advantage on dividends no longer helps.
- Neither works if you keep running the business from your home country without real management on the island.
If you are weighing a jurisdiction outside the EU as well, our comparison of Malta and Dubai covers the UAE.
Frequently asked questions
Is Cyprus corporate tax still 12.5%?
No. Cyprus raised its corporate income tax rate to 15% from 1 January 2026, with the tax reform laws published in December 2025.
Is Malta’s 5% effective tax still available in 2026?
Yes. The 35% rate with a six-sevenths refund on trading profits remains in force. Groups can pay it directly, without a refund claim, through a fiscal unit. Since 2024 profits companies can also choose a 15% final tax with no refunds, but the choice is optional.
Does Cyprus still apply the deemed dividend distribution?
Not on profits from 2026 onwards. The 70% deemed distribution still applies, on a transitional basis, to profits of 2024 and 2025.
Which country is better if I move there myself?
If you become a non-domiciled resident and pay yourself dividends, Cyprus is usually cheaper, because non-doms pay no SDC on dividends for 17 years. If you stay outside both islands and run a trading company, Malta usually costs less.
Do I need to live in Malta or Cyprus to use a company there?
No, but the company must be managed in the country where it is registered. If you run it from your home country, your home country can tax it.
Sources
- Cyprus Income Tax (Amendment) Law, L.244(I)/2025
- Cyprus Special Defence Contribution (Amendment) Law, L.245(I)/2025
- PwC Worldwide Tax Summaries, Cyprus
- PwC Worldwide Tax Summaries, Malta
- Malta, Consolidated Group (Income Tax) Rules, S.L. 123.189